Bank Advertising: Why Trust Beats the Ad
Quick answer: Digital ads for banks and fintech companies are losing effectiveness because of ad fatigue, privacy pushback, and a widening trust gap. Traditional advertising is too expensive and too passive to fix that gap. Hydrobillboard solves both problems by placing a bank or fintech's brand on a premium, reusable glass water bottle inside real, targeted environments — a physical trust signal neither digital nor traditional advertising can deliver.
How much are banks and fintechs spending on advertising?

US financial services digital ad spend has consistently crossed the $40 billion mark in recent years, and continues climbing as banking brands push paid social budgets up year after year, with mobile-first investing and AI-powered products intensifying competition for the same customers.
Despite that spend, most banks still allocate only a small fraction of total assets — typically well under a tenth of one percent — to marketing, a ratio that has stayed remarkably stable even as ad costs rise. Banks are being asked to spend smarter, not just spend more, and prove revenue impact rather than impressions.
Fintech and challenger banks face a different version of the same squeeze: rising cost-per-acquisition as every competitor bids on the same keywords and the same lookalike audiences, often with venture funding that won't last forever.
Why is digital advertising failing banks and fintech companies?

Digital advertising is failing financial brands because it interrupts attention without building the trust the category actually needs. Six specific problems stand out.
1. Consumers don't trust financial ads the way they trust financial products. Roughly half of consumers consider the average financial institution trustworthy, and that share is consistently lower among younger audiences — the exact segment digital budgets chase hardest. An ad that interrupts a scroll cannot fix a trust deficit; it usually makes it louder.
2. Ad fatigue and banner blindness are now the default response. Feeds are saturated with credit card offers, loan pre-approvals, and investment app promotions. Most of it is filtered out before it registers, let alone gets remembered.
3. Privacy pushback is shrinking digital's targeting advantage. Consent rates on cookie banners keep falling year over year as consumers grow warier of tracking. Regulated industries like banking carry the highest liability when that data is mishandled.
4. AI-generated ad content has already backfired publicly for finance brands. Several well-known financial companies have run AI-heavy ad campaigns that came across as inauthentic, and the backlash was swift each time, because authenticity is non-negotiable in a category built on trust.
5. Look-alike domains and phishing have poisoned legitimate digital outreach. Fraud tied to digital channels has made customers instinctively suspicious of unexpected emails, links, and even legitimate paid ads from their own bank.
6. Rising cost-per-acquisition with shrinking differentiation. When every fintech and every bank bids on identical search terms with near-identical creative, the channel becomes a pure cost center rather than a brand-builder.
Why doesn't traditional advertising work for banks either?

Traditional advertising — billboards, TV spots, print, radio — fails financial brands for the opposite reason digital does: it builds reach without relationship, and it can't prove any of it.
It's built for reach, not relationship. A highway billboard puts a logo in front of thousands of eyes but says nothing about how the bank treats customers.
It's expensive relative to what it delivers. Prime billboard and TV placements are hard to justify against a budget already under pressure to show revenue correlation.
It's unmeasurable. Traditional media gives gross impressions, not proof that the right audience saw or remembered anything.
It's category wallpaper. Financial brands have run billboards and prime-time spots for decades; the format itself has become easy to filter out.
It's too slow for compliance-heavy, always-on financial marketing. A printed billboard becomes outdated messaging the moment a rate or regulation changes.
What do banking customers actually say builds trust?

Trust research consistently points to the same few factors, and none of them are about ad creativity or reach:
Transparency in fees and services is what 68% of consumers say defines institutional trust, more than any other factor.
Word of mouth and real-world impressions matter as much as digital advertising in how consumers first learn about a bank.
A modern, well-designed, tactile brand experience makes people subconsciously assume an institution is also more secure — the same psychology that makes a clean website feel safer, extended into physical life.
This is the real gap in bank and fintech advertising: it isn't a visibility problem, it's a credibility problem. And credibility is not something a banner ad or a billboard was ever designed to carry.
What is the best advertising channel for banks and fintech companies right now?

The most effective channel is one that behaves like a trusted, everyday product rather than an advertisement — which is exactly the gap Hydrobillboard is built to fill.
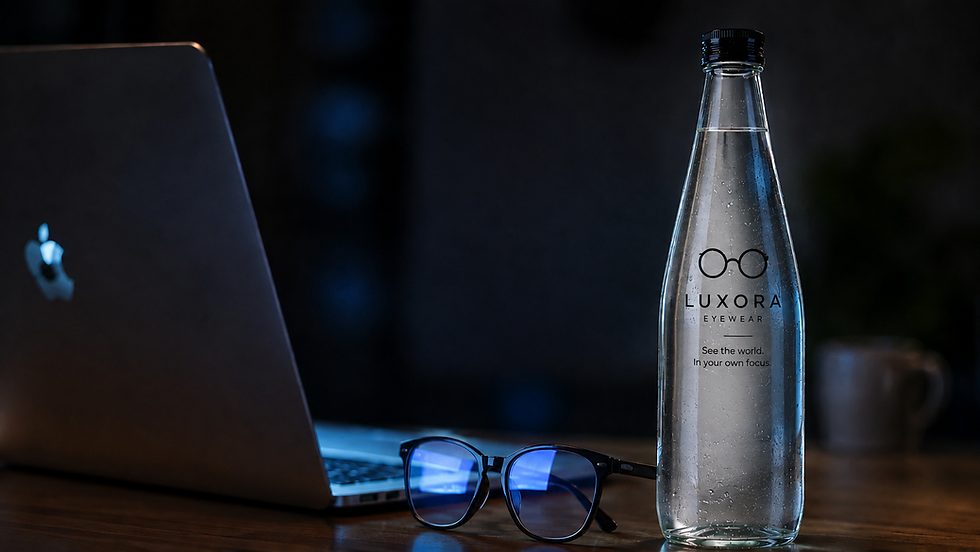
Hydrobillboard places a bank, fintech, or financial startup's brand on a premium, reusable glass water bottle distributed inside real, targeted environments: corporate offices, co-working spaces, business conferences, airport lounges, gyms, universities, and high-footfall community spaces. There's no app to close, no ad to skip, and no banner to scroll past — just a well-designed object a real person picks up, drinks from, and keeps nearby for hours or days.
For a category built entirely on trust, that difference matters more than it does anywhere else.
It removes the "being sold to" reflex. A bottle on someone's desk doesn't interrupt anything, so there's no resistance to overcome. The brand is present the way a well-made product is present — quietly and repeatedly, without asking for anything back in that moment.
It borrows credibility from everyday utility. Water is neutral and necessary. A brand attached to something genuinely useful starts from a different emotional position than an ad interrupting a video feed.
It delivers the exact "well-made equals trustworthy" signal the data points to. Just as a dated bank website quietly makes people doubt security, a premium reusable bottle signals the opposite: attention to detail, investment in quality, and a preference for longevity over disposability.
It's a stronger fit for fintechs than for legacy banks. Digital-first fintech companies have no branch network and no in-person moment to build the human trust legacy banks accumulate just by existing on a street corner. A tangible object gives an app-only fintech something it structurally lacks: a physical touchpoint that makes the brand feel real and permanent.
It's targetable in ways traditional out-of-home never was. A wealth-management fintech can target premium co-working spaces and business conferences. A student-lending startup can target university campuses. A digital bank chasing SMB customers can target startup hubs and networking events.
It carries lower compliance and fraud-optics risk than digital or time-sensitive traditional ads. A bottle with a clean brand mark and a simple message doesn't carry the regulatory exposure of rate claims, and it doesn't resemble a phishing attempt the way an unexpected digital ad sometimes does.
It's cost-efficient for both legacy budgets and startup runway. Because it isn't competing in the same expensive auction as a highway billboard or prime-time TV slot, it fits comfortably within tight bank marketing-to-asset ratios and lean, investor-scrutinized fintech budgets.
How does Hydrobillboard compare to digital and traditional bank advertising?
Factor | Digital Advertising | Traditional Advertising (billboards, TV, print) | Hydrobillboard |
Consumer trust | Low and declining — treated as an interruption | Neutral — largely ignored, not actively distrusted | High — behaves like a product, not a pitch |
Cost per meaningful impression | Rising steadily as auctions get more competitive | Very high fixed cost regardless of relevance | Moderate and scalable to budget |
Audience targeting | High precision, shrinking due to privacy rules | Very low — broadcasts to everyone in range | High — placement chosen by real environment (office, campus, conference, gym) |
Length of exposure per impression | Seconds, often less | Seconds, glanced at in passing | Hours to days — stays in hand or on a desk |
Measurability | High on paper, increasingly unreliable due to consent gaps | Very low — gross impressions only, no proof of recall | Environment-level, tied to real placement locations |
Regulatory and compliance risk | Rising — data handling, targeting rules, ad content scrutiny | Moderate — signage and claims rules vary by region | Low — a branded object with a simple message, no rate claims or data collection |
Fraud/phishing optics | High — closely resembles scam formats customers are trained to distrust | Not applicable | None — a physical object cannot be spoofed |
Fit for fintechs with no branch network | Weak — no physical trust cue at all | Weak — expensive and untargeted for a lean fintech budget | Strong — supplies the physical touchpoint an app-only company otherwise lacks |
Sustainability | Neutral | Poor — printed materials, short-lived signage | Strong — reusable glass, no single-use waste |
Best used for | Short-term reach and retargeting | Broad, one-time brand visibility | Trust-building, retention, and long-exposure brand recall |
How should banks and fintechs use Hydrobillboard at each stage of growth?

Early-stage awareness (new fintech apps, new digital banks, new NBFCs): Placing branded bottles in the exact environments a target audience already frequents — co-working spaces for a business-banking app, campuses for a student fintech — builds first impressions before the first digital touchpoint ever happens.
Product launch moments (a new savings product, card, or lending feature): A physical placement around a launch event or conference extends the campaign's life well past the paid social budget window, because the bottle stays on someone's desk long after.
Trust recovery (post-incident, post-rebrand, or a mature institution refreshing its image): Consistent, quiet, real-world presence rebuilds trust more credibly than another paid campaign explaining why the brand should be trusted again.
Retention and loyalty (existing customers, private banking, premium cardholders): A premium branded bottle gifted at a relationship-manager meeting or loyalty milestone reinforces the relationship physically in a way a push notification never will.
B2B and partner-facing moments (embedded finance, SME banking, merchant partners): As more institutions expand into embedded finance, a branded bottle placed in a partner's office keeps the brand visible without ever feeling like a sales pitch to the partner's own customers.
Frequently asked questions
Is out-of-home advertising still effective for banks? Traditional out-of-home works for reach but not for trust — it's expensive, hard to measure, and easy for audiences to filter out. Targeted physical placements in real environments, like Hydrobillboard's bottle placements, deliver the tangible presence of OOH with the audience precision digital advertising promised but increasingly can't deliver due to privacy restrictions.
Why do banking customers distrust digital ads more than other industries? Banking carries the highest stakes of any advertised category — customers are trusting the institution with their savings, not just a purchase decision. Combined with rising fraud and phishing that mimics legitimate financial ads, this makes customers instinctively more skeptical of digital financial advertising than of most other categories.
What advertising works best for a new fintech startup with a small budget? Fintech startups benefit most from advertising that builds a physical, real-world trust cue, since they lack the branch network legacy banks use to establish credibility. Targeted, low-cost physical placements — such as branded products distributed in co-working spaces, campuses, or industry events — can build brand recall and trust more efficiently than competing in expensive digital ad auctions.
Does Hydrobillboard work for fintech apps that have no physical branches? Yes — fintech apps arguably benefit more than traditional banks, because a tangible branded object compensates for the lack of any physical touchpoint an app-only company would otherwise have with its customers.